The April 18th issue of New York Magazine titled "The Post-Crash: Wall Street Won...
So why is it so worried?" investigates the effects of the 2008 financial crisis on the minds of Wall Street bankers, financiers, and money managers. Three articles, in particular, shed light into the ecstatic, neurotic, and perhaps deluded psychology of the post-crash financier. The articles raise a number of interesting points, which in-turn lead to a number of interesting questions: 1) what have financial organizations and entrepreneurs learned from the 2008 financial crisis?; 2) will there be any changes in the cultural norms on Wall Street?; 3) how can regulators attempt to reign in a financial sector that has return to its pre-crisis power?; and 4) if individuals on Main Street once again see that their pensions and retirement portfolios are increasing in value, then will they support strong legislation that restricts the financial sector?
The following is an excerpt from "The Wall Street Mind: Triumphant…" At the end of March, Neil Barofsky, on his final day as the special inspector general of the Troubled Asset Relief Program (TARP), published a scathing indictment of the program over which he’d served as watchdog since its inception in that awful, apocalyptic autumn of 2008. On the op-ed page of the New York Times, Barofsky argued that TARP had “failed to meet some of its most important goals”: protecting home values, easing the foreclosure crisis, alleviating the credit crunch—helping Main Street, in other words. Indeed, only when it came to aiding Wall Street had TARP worked like a charm. “Billions of dollars in taxpayer money allowed institutions that were on the brink of collapse not only to survive but even to flourish,” he wrote. “These banks now enjoy record profits and the seemingly permanent competitive advantage that accompanies being deemed ‘too big to fail.’ ”
Without necessarily intending to, Barofsky’s op-ed provided the perfect coda for the era of bailout rage—a two-and-a-half-year spasm of populist fury that promised, or threatened, to inflict enormous changes on the financial sector. In the political realm, Wall Street faced the prospect of root-and-branch reregulation, up to and including the potential nationalization of the industry’s largest players, and in the cultural realm its transfiguration into a kind of pariah state. Once upon a time, the Street’s leading lights had been glamorized and admired to the point of worship; now the likes of Robert Rubin, Lloyd Blankfein, and Richard Fuld were relentlessly pilloried and demonized. Once the megabanks were seen as indomitable powerhouses and sources of “financial innovation” (whatever the hell that was); now the greatest and most fearsome of them all, Goldman Sachs, was recast—by a famous and infamous Rolling Stone screed—as a “great vampire squid.”
Yet today on Wall Street, all of that seems a very long time ago. Not only are the banks rolling in dough again, but their denizens’ customs and sense of self-esteem have largely reverted to the status quo ante. With the enactment of a financial-reform law that is widely seen as toothless, the peril posed by government intervention has receded, and with it the industry’s concerns about the vicissitudes of public opinion. Vampire squids? That’s so 2009—an eon ago in Wall Street time. We won, you lost, get over it, is the prevailing attitude.
A mixture of indifference to and disdain for the views of outsiders has, of course, always been a feature of Wall Street culture—an inevitable outgrowth of the industry’s profound insularity. “Most bankers haven’t a clue what the rest of the world thinks of them,” says Henry Blodget, the fallen Merrill Lynch analyst now reborn as a bumptious web entrepreneur. “Wall Street is its own world, with its own tribes, its own customs, and its own pay scales, which are otherworldly. Once you’re in that world, what matters most is your place in that world, not what the rest of the world thinks of you. Given their druthers, bankers would not choose to be loathed and ridiculed. But in the hierarchy of priorities, this concern comes at the end of a long list of concerns that starts with this year’s bonus.”
Now, you might think that, given the gargantuan havoc they wreaked on the global economy and the vicious backlash it inspired, the bankers might have engaged in a modicum of self-scrutiny over these past months—and in the process arrived at, if not enlightenment, then at least a mildly less exalted conception of their own value and virtue. But this supposition presumes at once a degree of reflectiveness never much in evidence on Wall Street and a sense of culpability for the crash that was equally unapparent even at its depths.
“This is a profession with a lot of smart people, but who aren’t necessarily terribly introspective,” says one of the city’s most prominent private-equity kingpins. “They think they actually deserve to make all this money. [And] they created for themselves a narrative where the irrational actions by a few people caused the meltdown. None of them were sitting there saying to themselves, ‘I was responsible for this crisis. Shame on me.’ ”
None of which is to say that the bankers were utterly impervious to the loud calls for their decapitation. “The crisis momentarily alerted Wall Streeters to the fact that the rest of world is flabbergasted and appalled by how much money everyone makes,” Blodget says. “This revelation was startling to Wall Street, and with the threat of incarceration [and reregulation] on the table, it led to a temporary focus on relative decorum. But that’s all over now, so Wall Street has cheerfully gone back to doing what it’s great at.” (read more)
The goal of this blog is to critically reflect on the social, cultural, and political foundations of market societies. In particular, the objective is to spur discussion on how the current economic systems around the globe are constructed, what institutional and structural problems have developed, and how these problems can be fixed to create a better functioning economy and society.
Monday, April 11, 2011
Tuesday, April 5, 2011
A Shifting Economics Paradigm?
The 2008 financial crisis shook the foundations of our society and how we think about the interconnectedness of economy and society. An important force in shaping how we think of the economic system is the economics discipline. Economics has historically built the conceptual and theoretical models that have influenced economic policy by our nation's leaders and central banks, and firm's strategies in the market. These dominant ways of thinking--paradigms--hindered most economists from accurately predicting the near-collapse of the financial markets and the broader shocks to the credit and housing markets. As a result, many argue that the profession is partly responsible for the crisis and must re-evaluate how it approaches the study of the economy. The dominant paradigm of the economics profession has been called into question. There is, however, a new community of scholars who are trying to nudge the economic's profession in a new direction and to shift the dominant paradigms that underlie it forward--The Institute for New Economic Thinking.
INETeconomics--It’s time everybody recognized that our 20th century economic thinking is not fit for life as we know it in the 21st century.
The prevailing thinking, that the economy is an idealized system of perfectly rational, optimizing individuals and institutions, who, by trading in markets, bring the economy to a balanced, efficient equilibrium has been rendered obsolete by developments in recent years.
Markets are global. Money moves instantaneously 24/7, and is now a raw material for financial innovations. Regulators are fallible and market participants frequently fall below the standard of being perfectly rational.
Economic thinking has not kept up with these and other developments that now define us, and that fact deeply affects everyone – as we learned in our most recent global financial crisis.
Spurred by the financial crisis and recent developments in the economics field, a far more realistic view of the economy is emerging that takes into account imperfections in individuals, institutions, and information, as well as the existence of complex global networks of interaction, and the dynamism of innovation.
This “new economic thinking” has the potential to profoundly impact society in areas ranging from government policy and financial system reform, to solving climate change, poverty and inequality, and driving sustainable growth in the long run. In other words, new economic thinking can enable a better world for all.
The Institute for New Economic Thinking’s mission is to nurture a global community of next-generation economic leaders, to provoke new economic thinking, and to inspire the economics profession to engage the challenges of the 21st century.
Wednesday, March 30, 2011
A Self-Fulfilling Prophecy: The Bailout Of Fannie And Freddie
A great three-part series on Fannie Mae and Freddie Mac done by NPR and Planet Money provides a nice empirical example of the causal mechanism of self-fulfilling prophecy. A self-fulfilling prophecy as a concept has been around for centuries but was crystalized in the work of Robert K. Merton--the 20th century sociologist and social theorist. In his book Social Theory and Social Structure, Merton gives the following example of the self-fulfilling prophecy: when Roxanna falsely believes her marriage will fail, her fears of such failure actually cause the marriage to fail.
The self-fulfilling prophecy is, in the beginning, a false definition of the situation evoking a new behaviour which makes the original false conception come 'true'. This specious validity of the self-fulfilling prophecy perpetuates a reign of error because the prophet will cite the actual course of events as proof that he was right from the very beginning. In other words, a prophecy declared as truth when it is actually false may sufficiently influence people, either through fear or logical confusion, so that their reactions ultimately fulfill the once-false prophecy.
NPR--By the beginning of the 21st century, almost half of all the mortgages in America were made through Fannie and Freddie. Fannie and Freddie were private companies, with shareholders and highly paid CEOs. But they'd achieved this dominance because of the implicit guarantee they had from the U.S. government. Because the world believed the government stood behind them, Fannie and Freddie paid less to borrow money than any other financial institution in the country. This gave them a big advantage.
Despite the fact that the implicit guarantee had turned Fannie and Freddie into two of the largest and most powerful companies in US history, people continued to deny that the guarantee existed. At the top of every security that Fannie and Freddie issued, right there in big black letters, it said, "This security is not backed by the U.S. government." High-powered government officials from both parties also denied that the guarantee existed. In 2003, Democratic congressman Barney Frank put it this way:
There is no guarantee. There's no explicit guarantee. There's no implicit guarantee. There's no wink-and-nod guarantee. Invest and you're on your own. Nobody who invests in them should come looking to me for a nickel. Nor anyone else in the federal government.
And in public, Fannie and Freddie would "adamantly lash back at anybody who argued that there was in fact a government subsidy," according to New York Times columnist Joe Nocera.
But to some of the people who mattered — the ones who were buying Fannie and Freddie securities — the companies said something else entirely. Scott Simon was one of those buyers. He works in the mortgage department at Pimco, the world's largest bond manager, and one of the biggest buyers of Fannie and Freddie securities:
"Fannie and Freddie in meetings with investors, whether it was us or anybody else, essentially just would sort of laugh and say, 'Well, you know the government will stand behind us,'" Simon says.
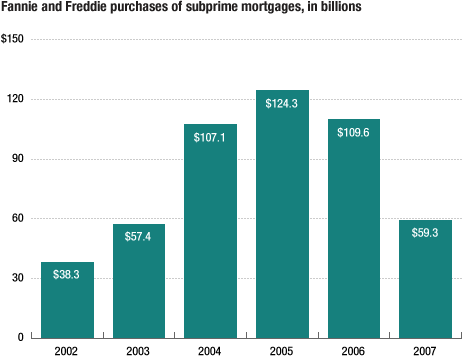
Truer words were never secretly spoken. But when the bailout finally did happen, it happened in a way almost no one would have foreseen. For decades, Fannie and Freddie had used their implicit government guarantee to get huge and powerful. But they got huge and powerful in a pretty boring way. They dealt mostly with standard, 30-year, fixed-rate loans. Borrowers had to document their employment and income, and most made a down payment of 10 to 20 percent. But then, in the mid-2000s, subprime lenders came on the scene, making loans to people with no income and no jobs.
This kind of easy money made going through all the work to get a Fannie or Freddie loan unappealing for many borrowers, according to Barry Zigas, who was an executive at Fannie Mae during this time. Imagine a customer going through the lengthy process of qualifying for a Fannie Mae loan, scraping together a down payment, showing up at the bank office, with all the requisite documents in tow.
"And they walk out and in the parking lot is a broker saying, 'Would you like a home loan? Cause let's sit down right here in my car.... We'll do the paperwork right now.' Which was literally what was happening," Zigas says. "And as a consequence, the Fannie Mae share of the market in mortgage backed securities dropped."
We now know that the subprime broker in the parking lot was a sign that we were in the midst of the largest housing bubble in national history. But at the time, folks at Fannie and Freddie had no idea what was going on. These subprime companies that had been around for just a couple years, that had no government guarantee, were stealing Fannie and Freddie's customers.
And this is the point where the hybrid nature of Fannie and Freddie came back to haunt them. Because, remember, they had private shareholders. And those private shareholders were not happy with Fannie and Freddie's falling market share.
So, after much hand-wringing and internal soul-searching, Fannie and Freddie decided they would follow the subprime industry into the abyss. Fannie and Freddie started accepting lower credit scores, stopped requiring proof of income from all borrowers, and invested in securities made up of subprime loans.
It was "total corporate delusion," says journalist Bethany McLean. "It wasn't actually until really the summer of 2008, when everybody kind of realized the obvious, which was: The mortgage market is falling apart. Fannie and Freddie are the biggest players in the mortgage market. Oh my goodness, what are we going to do?" (read more)
Saturday, March 26, 2011
Negative Consequences of an Increasing Financialization of Society
The Kauffman Foundation recently released a paper that evaluates how growing wage and skill premiums in finance suppress innovation and entrepreneurship for the larger U.S. society.
March 25, 2011 – The expansion of the financial sector over the past few decades shifted the flow of capital toward financial assets, creating inefficiencies that had material economic impacts, according to "Financialization and Its Entrepreneurial Consequences," a study the Ewing Marion Kauffman Foundation released today.
One of those impacts may have been the financial industry's effect on entrepreneurship. Although widespread entrepreneurial capitalism requires a significant and active financial services sector, the industry's growing size potentially suppressed entrepreneurship as financial services and young companies compete for many of the same employees, according to the study.
The financial sector, which includes lending, stock brokerage, complex securities and insurance, among many other services, derives enormous profits from collateralized debt obligations. These new products require such sophisticated engineering that the industry now focuses its recruiting on new master's- and doctoral-level graduates of science, engineering, math and physics, and pays them starting wages that are five times or more what they would have earned had they remained in their own fields.
"Because these new hires are often the very individuals who otherwise would have comprised the most robust pool of prospective founders of high-growth companies, the financial services industry's steady rise has had a cannibalizing effect on entrepreneurship in the U.S. economy," said Paul Kedrosky, Kauffman Foundation senior fellow and one of the paper's authors. "Excessive financialization exacerbated and distorted the flow of capital in the economy, potentially suppressing entrepreneurship by drawing away entrepreneurial talent."
History has shown that human and other capital inevitably flows to the opportunities that provide the highest risk-adjusted returns. Regulations and feed processes can change these capital allocations, however, tilting the balance by starving some sectors and opportunities, while creating a flood of capital for others, leading to inflated or deflated asset prices, reduced productivity, less innovation and less entrepreneurship, thus lowering job creation and overall economic growth.
"While the rate of entrepreneurship fell and then flattened over the past two decades, financialization also likely affected the caliber of startups," said Dane Stangler, Kauffman research manager and co-author of the paper. "An excessively dominant financial sector may have made it easier for weaker (or potentially weaker) companies to obtain financing, thus helping to maintain that steady rate of entrepreneurship but possibly contributing to the declining quality of newly established businesses."
When the financial sector shrinks as a share of GDP, as it is likely to do in the near future, the study predicts it will coincide with a number of other trends and help increase the rate of new business creation, as well as providing an environment for higher social value from new companies. The authors note that while a "smaller" financial services sector will be smaller relative to recent history, it still likely will be larger than in prior decades, meaning that it could continue to provide the financial intermediation services young companies need most.
A smaller financial sector also should improve allocative efficiency among technical graduates, and among financial services employees who lose their jobs in the industry but respond by establishing companies that otherwise might not have existed.
Spread of Insider Information Within Social Networks
Recent crack downs by the SEC have shown that the spread of insider information within networks of financial organizations has become ubiquitous. Luigi Zingales, Professor of Entrepreneurship and Finance at University of Chicago Graduate School, has a recent article that points out that the spread of insider information is happening at the highest levels of the financial world.
CHICAGO: If you thought that America’s financial sector had gotten enough of bad publicity, think again. The insider-trading trial of Raj Rajaratnam, a billionaire hedge-fund manager, has now begun. It is likely to provide an especially lurid exposé of the corrupt underbelly of the financial world.
Rajaratnam’s trial is remarkable in many ways. First, it is one of the few insider-trading cases ever to be brought against a professional hedge-fund manager. Historically, both state and federal attorney generals have preferred to prosecute “occasional” traders, who stick out like a sore thumb.
For example, when a tiny Italian bank received from someone who never traded a large order for shares of US Shoe shortly before the company was acquired by Italian eyewear maker Luxottica, it was not difficult to smell a fish. In other words, precisely because occasional traders trade rarely, it is much easier to prove the nexus of causality between their trades and an illegal tip. By contrast, it is much more difficult to identify a problem when a person makes hundreds of trades every day.
In Rajaratnam’s case, the possibility of establishing such a link has come through telephone surveillance. This is the trial’s second remarkable aspect: it is the first insider-trading case to rely on an instrument generally reserved for pursuing drug or mafia cases. When the contents of these conversations are revealed in court, they will not allay the public’s already considerable distrust of the financial sector, to say the least.
But the most remarkable aspect of this case is the level of the people involved. Past insider-trading prosecutions of people other than occasional traders usually involved rogue financiers, like Ivan Boesky in the 1980’s.
This time, we are talking about the very heart of corporate America. A managing director of McKinsey, Anil Kumar, has already pled guilty to providing inside information to Rajaratnam in exchange for cash payments of at least $1.75 million. Raja Gupta, McKinsey’s worldwide managing director for nine years, is accused of being one of the conspirators, as is Rajiv Goel, a managing director of Intel.
It is so difficult to imagine that successful executives would jeopardize their careers and reputations in this way that many of us probably hope that the accusations turn out to be without merit. But recent academic research – by Lauren Cohen, Andrea Frazzini, and Christopher Malloy – shows that it is not far-fetched that university friends like Kumar, Goel, and Rajaratnam would get together to share confidential information.
This research shows that portfolio managers place larger bets on firms that have directors who are their college friends and acquaintances, earning an 8% excess annual return. A benign interpretation of these results is that college mates know each other better; thus, a portfolio manager has an advantage in judging the quality of the CEO if they spent time with him or her in college. But this benign interpretation is difficult to reconcile with the finding that these positive returns are concentrated around corporate news announcements.
After ten weeks of a trial like this, it will be easy for the public to conclude that all hedge funds are crooked, and that the system is rigged against the outsiders. Fortunately, this is not the case. While there are certainly some rotten apples in the hedge-fund industry, the majority of traders behave properly, and their legitimate research contributes to making the market more efficient.
Nevertheless, it will be difficult for legitimate hedge-fund managers to remove the taint that rogue traders have now spread over their industry. One way to do this is to be proactive in their disclosure. Hedge funds should publicly report all past trades that are at least two years old. Such delayed disclosure would not weaken their competitiveness, since the half-life of most trading strategies is very short, but it would give them the credibility that comes with having nothing to hide.
Voluntary public disclosure by hedge funds could also prevent a much stronger regulatory intervention that might otherwise cling to the alarming headlines generated by Rajaratnam’s trial.
Friday, March 25, 2011
Global Markets are Embedded in National Systems of Governance
Over at The American Prospect, Robert Kuttner has a nice article this month that argues that some of the leading mainstream economists are starting to embrace the realization that markets are embedded in social and political systems, and are dependent on them for stability and growth.
March 15th, 2011: By training, economists tend to be uncomfortable with politics. In the purest version of the standard economic paradigm, political interference by narrow interests or clumsy bureaucrats distorts the efficiencies of markets. Since the financial collapse, that narrative has necessarily been on the defensive. Even so, most of the profession remains wedded to the master story of market efficiency -- and nowhere more emphatically than in the area of the global economy where an outmoded idiom of "free trade" versus "protectionism" still reigns. Radical political economists have never bought this story, but revisionism by mainstream economists is still relatively novel and risky to one's career.
Dani Rodrik is an economist of impeccable credentials, with a doctorate from Princeton and a Harvard chair in international political economy. His new book, The Globalization Paradox, is simply the best recent treatment of the globalization dilemma that I've read, by an economist or anyone else. The paradox of his title is the fact that markets need states, but states are weakened, perhaps fatally, as globalization advances. When they promote ever deeper globalization, economists undermine the very markets they cherish as well as the state's capacity to reflect the democratic wishes of its citizens.
In 1997, a younger Rodrik wrote a more tentative critique, Has Globalization Gone Too Far?, which addressed the disruptive effect of globalization on domestic well-being, as brokered by democratic states. In this new volume, he gives us nothing less than a general theory of globalization, development, democracy, and the state. The book provides the pleasure of following a thoughtful, critical mind working through a complex puzzle. Rodrik writes in highly friendly and nontechnical prose, blending a wide-ranging knowledge of economic history and politics and a gentle, occasionally incredulous, skepticism about the narrow and distorting lens of his fellow economists.
Rodrik begins by observing that when you look at actual economic history, "markets and states are complements, not substitutes." Over the past three centuries, some states have facilitated economic development well, and some have done it badly, but there is no successful case of pure laissez-faire. He recounts the history of governments as enablers of global commerce, the hypocrisy of nations such as Britain that commended free trade but benefited from colonies, and the actual extensive role of the state in promoting business. Next, he describes how most economists just get this story wrong, either because they can't bring themselves to study the messy details of politics and history or because they cling deductively to assumptions rather than addressing evidence.
Turning to a rare moment when sensible economic theory was married to good economic practice, Rodrik invokes the postwar Bretton Woods era as an ideal middle ground, when statesmen devised a balanced system that promoted foreign commerce but recognized the necessary role of the state as an agent of development, stability, and democracy: "A delicate compromise animated the new [global] regime: allow enough international discipline and progress toward trade liberalization to ensure vibrant world commerce, but give plenty of space for governments to respond to social and economic needs at home. ... The goal would be moderate globalization, not hyperglobalization." Looking back at the past century and the headlong rush to ever deeper globalization, he concludes, "A 'thin' version of globalization, a la Bretton Woods, seems to work best."
The trade regime of the early postwar years allowed government interventions that were plainly inconsistent with both the norm of free trade and the subsequent stampede to hyperglobalization. Those interventions included state subsidies, anti-dumping duties, the wholesale exclusion of textiles and agriculture from rules of liberal trade, moderately high tariffs, and tight national regulation of global capital movements or speculation in currencies. But the system worked. It allowed high levels of growth and permitted democratic states to respond to the demands of citizens. "Until the 1980s," Rodrik wrote in a 2000 article, "these loose rules left enough space for countries to follow their own ... paths of development."
After the fixed exchange rates of the Bretton Woods system collapsed, mainly because the dollar was in the unsustainable role of both a national currency and a global one, the middle ground of "moderate globalization" collapsed with it. A newly fundamentalist economics profession became a scholarly lobby for laissez-faire trade, while business elites lobbied for deep globalization to escape the regulatory constraints of states. "Domestic economic management was to become subservient to international trade and finance, rather than the other way around."
Developing countries, nonetheless, went right on violating the practice of laissez-faire, and their state-led development served them well. Mainstream economists preserved their theories only by leaving out Asia. Yet the rush to deep globalization continued. The "hyperglobalizers," Rodrik demonstrates, suffered from two fatal blind spots: "One was that we could push for rapid and deep integration of the world economy and let institutional underpinnings catch up later. The second was that hyperglobalization would have no, or mostly benign, effects on domestic institutional arrangements."
The folly of financial globalization underscored why the conventional wisdom was catastrophically wrong. The costs in increased instability far outstripped any efficiency gains. Global finance, Rodrik says, outran national regulation: "Domestic finance is underpinned by common standards, deposit insurance, bankruptcy rules, court-enforced contracts, a lender-of-last resort, a fiscal backstop, [and] regulatory and supervisory agencies. None of these exists globally."
Given the implausibility of global government and the abysmal failure of partial global regulatory regimes such as the Basel Accords on capital standards, the nation state is still the only game in town, says Rodrik: "The scope of workable globalization limits the scope of desirable globalization." Summing up elegantly, Rodrik defines a "trilemma." Despite the beau ideal of most of the economics profession, it is not possible to have deep globalization and political democracy and a competent nation state. At most, you can have two out of three. "Ultimately," Rodrik says, the quest for global governance leaves us with too little real governance." Rodrik's plea is for us to give up the dangerous fantasy of deep globalization to preserve the state as instrument of democracy and an efficient mixed economy. According to Rodrik, the "golden straitjacket" commended by Thomas Friedman, of a single set of rules and norms to attract global capital, is a straitjacket all right, but a disastrous one.
In his final chapters, Rodrik calls for a Capitalism 3.0 -- a mixed system in the spirit of Bretton Woods. Though I could quibble with some details, his basic principles are spot-on: "Markets must be deeply embedded in systems of governance. ... There is no 'one way' to prosperity. ... Countries have the right to protect their own social arrangements, regulations, and institutions. ... Non-democratic countries cannot count on the same rights and privileges in the international economic order as democracies."
Rodrik has done an immense service by reconnecting economics to politics, reviving an older tradition of political economy and generalized social science. One area he leaves out, however, is the politics of why deep globalization keeps gaining ground despite its practical failures -- specifically, its distorting effect on deliberation within the democracies. Had he ventured even further into the political thicket, he might have shed more light on the hegemonic alliance that links the economics profession, political elites, the global business class, and its low-wage partners in developmental states. Overthrowing this perverse paradigm in practice will be even more difficult than demolishing it in theory, as Rodrik has so elegantly done. (read more)
Wednesday, March 23, 2011
America's New Shadow Democracy
A new report by the People For the American Way (PFAW) has been released that investigates the negative effects of the Citizens United v. FEC ruling for U.S. Democracy. The Supreme Court’s 5-4 ruling in Citizens United v. FEC (2010) held that the First Amendment right of free speech applies with little distinction to both individuals and corporations. Since Buckley v. Valeo (1976) established campaign spending as a form of protected speech, the Court’s decision allows for corporations to engage in political spending and to donate unrestricted funds from their general treasuries to other political organizations, effectively overturning decades of state and federal campaign finance laws. Fearing effects of greater corporate influence on American political democracy, Justice Stevens in his dissenting opinion warned that corporations can “amass and deploy financial resources on a scale few natural persons can match,” but are not “themselves members of ‘We the People’ by, whom, and for whom our Constitution was established.”
Although “we the corporations” now have a constitutional right to contribute money to independent expenditure groups, they are not bound to publicly disclose the sources of their funding. Even though the majority opinion in Citizens United upheld Congress’s right to enact disclosure laws, acknowledging that such “transparency enables the electorate to make informed decisions” without “impos[ing] a chill on speech or expression,” today’s 501 (c)4 and (c)6 organizations are under no obligation to disclose their their financial backers but are increasingly engaged in electioneering advocacy across the country.
While we do not know who is funding such organizations, we do know that the groups which played a significant role in the 2010 elections are overwhelmingly backing right-wing candidates. “Outside groups raised and spent $126 million on elections without disclosing the source,” according to the Sunlight Foundation, which “represents more than a quarter of the total $450 million spent by outside groups.” Republican candidates largely benefited from the downpour of undisclosed money, as pro-GOP groups that did not reveal their donors outspent similar pro-Democratic groups by a 6:1 margin. The nonpartisan Center for Responsive Politics reports that of the top ten groups which did not disclose their sources of funding, eight were conservative pro-GOP organizations.
A post-election report by Politico found that organizations such as Crossroads GPS, the US Chamber of Commerce, the 60 Plus Association, and the American Action Network, “backed by millions in corporate cash and contributions by secret donors,” coordinated with each other and the National Republican Congressional Committee to ensure that “vulnerable Democrats got the full brunt of GOP spending.” By coordinating their political activities, many of these groups were able to increase the number of Democrats facing a deluge of negative advertisements, making Democrats in once-safe seats more vulnerable to defeat.
Citizens United and related judicial and administrative decisions have also allowed for the emergence of so-called Super PACs, which can take in unlimited amounts of money from corporations and individuals. A number of the new political organizations have been exposed as front groups for the oil and gas and insurance industries and Wall Street moguls, and new revelations reveal that some groups even receive substantial funding from federal government contractors and foreign businesses. Corporate dollars are also financing many Tea Party and other conservative “grassroots” organizations, giving “astroturfing” an even more prominent role in American politics.
The Center for Responsive Politics reported that conservative outside groups spent $188.8 million in 2010, while left-leaning groups spent less than half that amount. In the last ninety days of the election, the twenty largest conservative outside groups ran 144,182 television ads, and seventy-seven percent of those ads came from organizations which do not disclose their donors.
Legislative remedies, most notably the currently stalled DISCLOSE Act, will bring more transparency to the process while still leaving corporate intervention in electoral politics mostly intact. Due to the sweeping language of the Supreme Court’s ruling in Citizens United, only a constitutional amendment can effectively overturn the decision.
This report looks into the groups that, armed with the 5-4 Citizens United decision, promoted their pro-corporate agenda and built a wall of conservative propaganda across America during the recent election cycle. Many groups originated in the aftermath of Citizens United and directly cite the ruling as essential to their founding; others had been active for years but gained new funding, energy and prominence as a result of the decision. What they all had in common was a relentless desire to discredit progressive ideas and elect pro-corporate candidates to office across the country. As discussed below, they also shared an alarming tactical bent for deceitfulness and distortion in the campaign process. (read more)
Wednesday, March 2, 2011
The Poverty of Dictatorship by Dani Rodrik
CAMBRIDGE – Perhaps the most striking finding in the United Nations’ recent 20th anniversary Human Development Report is the outstanding performance of the Muslim countries of the Middle East and North Africa. Here was Tunisia, ranked sixth among 135 countries in terms of improvement in its Human Development Index (HDI) over the previous four decades, ahead of Malaysia, Hong Kong, Mexico, and India. Not far behind was Egypt, ranked 14th.
The HDI is a measure of development that captures achievements in health and education alongside economic growth. Egypt and (especially) Tunisia did well enough on the growth front, but where they really shone was on these broader indicators. At 74, Tunisia’s life expectancy edges out Hungary’s and Estonia’s, countries that are more than twice as wealthy. Some 69% of Egypt’s children are in school, a ratio that matches much richer Malaysia’s. Clearly, these were states that did not fail in providing social services or distributing the benefits of economic growth widely.
Yet in the end it did not matter. The Tunisian and Egyptian people were, to paraphrase Howard Beale, mad as hell at their governments, and they were not going to take it anymore. If Tunisia’s Zine El Abidine Ben Ali or Egypt’s Hosni Mubarak were hoping for political popularity as a reward for economic gains, they must have been sorely disappointed.
One lesson of the Arab annus mirabilis, then, is that good economics need not always mean good politics; the two can part ways for quite some time. It is true that the world’s wealthy countries are almost all democracies. But democratic politics is neither a necessary nor a sufficient condition for economic development over a period of several decades.
Despite the economic advances they registered, Tunisia, Egypt, and many other Middle Eastern countries remained authoritarian countries ruled by a narrow group of cronies, with corruption, clientelism, and nepotism running rife. These countries’ rankings on political freedoms and corruption stand in glaring contrast to their rankings on development indicators.
In Tunisia, Freedom House reported prior to the Jasmine revolution, “the authorities continued to harass, arrest, and imprison journalists and bloggers, human rights activists, and political opponents of the government.” The Egyptian government was ranked 111th out of 180 countries in Transparency International’s 2009 survey of corruption.
And of course, the converse is also true: India has been democratic since independence in 1947, yet the country didn’t begin to escape of its low “Hindu rate of growth” until the early 1980’s.
A second lesson is that rapid economic growth does not buy political stability on its own, unless political institutions are allowed to develop and mature rapidly as well. In fact, economic growth itself generates social and economic mobilization, a fundamental source of political instability.
As the late political scientist Samuel Huntington put it more than 40 years ago, “social and economic change – urbanization, increases in literacy and education, industrialization, mass media expansion – extend political consciousness, multiply political demands, broaden political participation.” Now add social media such as Twitter and Facebook to the equation, and the destabilizing forces that rapid economic change sets into motion can become overwhelming.
These forces become most potent when the gap between social mobilization and the quality of political institutions widens. When a country’s political institutions are mature, they respond to demands from below through a combination of accommodation, response, and representation. When they are under-developed, they shut those demands out in the hope that they will go away – or be bought off by economic improvements.
The events in the Middle East amply demonstrate the fragility of the second model. Protesters in Tunis and Cairo were not demonstrating about lack of economic opportunity or poor social services. They were rallying against a political regime that they felt was insular, arbitrary, and corrupt, and that did not allow them adequate voice.
A political regime that can handle these pressures need not be democratic in the Western sense of the term. One can imagine responsive political systems that do not operate through free elections and competition among political parties. Some would point to Oman or Singapore as examples of authoritarian regimes that are durable in the face of rapid economic change. Perhaps so. But the only kind of political system that has proved itself over the long haul is that associated with Western democracies.
Which brings us to China. At the height of the Egyptian protests, Chinese Web surfers who searched the terms “Egypt” or “Cairo” were returned messages saying that no results could be found. Evidently, the Chinese government did not want its citizens to read up on the Egyptian protests and get the wrong idea. With the memory of the 1989 Tiananmen Square movement ever present, China’s leaders are intent on preventing a repeat.
China is not Tunisia or Egypt, of course. The Chinese government has experimented with local democracy and has tried hard to crack down on corruption. Even so, protest has spread over the last decade. There were 87,000 instances of what the government calls “sudden mass incidents” in 2005, the last year that the government released such statistics, which suggests that the rate has since increased. Dissidents challenge the supremacy of the Communist Party at their peril.
The Chinese leadership’s gamble is that a rapid increase in living standards and employment opportunities will keep the lid on simmering social and political tensions. That is why it is so intent on achieving annual economic growth of 8% or higher – the magic number that it believes will contain social strife.
But Egypt and Tunisia have just sent a sobering message to China and other authoritarian regimes around the world: don’t count on economic progress to keep you in power forever.
Wednesday, February 23, 2011
Revolution in Cairo: The Power to Organize
FRONTLINE just released an investigative report that gives a behind the scenes look at two organizations at the center of the Revolution in Cairo--the secular youth movement and the muslim brotherhood. Overall, the report gives great insight into how organizational power and the power to organize came together in a unifying force that toppled a 30+ year dictator. The missing social force behind the Revolution in Cairo, which was only briefly eluded to in the FRONTLINE portrayal, was the Egyptian people who had experienced economic hardships and political repression. For example, for years the Egyptian economy has been struggling with economic inequality, inflation, unemployment, and poverty. Thus, while the two dominant organizational groups--secular youth movement and muslim brotherhood--used their power to organize successfully, the full story needs to take into account the large economically deprived population of the Egyptian Society that fundamentally were the foot soldiers in the Revolution in Cairo.
As the protest movement in Egypt sent shock waves throughout the country -- and the world -- FRONTLINE dispatched teams to Cairo for this special report. "This is a story that no one could have predicted, and everyone now wants to know more about," says FRONTLINE executive producer David Fanning. "We're using our new monthly magazine to be able to respond quickly to timely events and help fill the need for added depth and insight on these important breaking stories."
In this hour's lead story, Revolution in Cairo, FRONTLINE gains unique access to the April 6 Youth Movement as they plot strategy, then head out into Cairo's Tahrir Square, hoping to bring down President Hosni Mubarak. The film traces these young Egyptian activists' long road to revolution, as they made increasingly bold use of the Internet in their underground resistance over the last few years. Through sites like Facebook, Twitter and YouTube, the members of April 6 and related groups helped organize a political movement that the secret police did not understand and could not stop, despite the arrest and torture of some of the movement's key members.
For the second story, The Brothers, veteran Middle East correspondent Charles Sennott of GlobalPost is on the ground in Cairo for FRONTLINE to investigate the Muslim Brotherhood, the controversial but poorly understood Islamist political movement that's poised to play a key role in Egypt's future. While the group was absent in Tahrir Square when young demonstrators first ignited Egypt's revolt, the Brotherhood assumed a larger role over the course of the protests, taking frontline positions in rock-throwing battles with regime supporters and helping to run emergency medical clinics. Now that the Muslim Brotherhood stands to take a prominent place at the negotiating table, we examine what the group believes and how it may influence politics in the country and the region.
Tuesday, February 22, 2011
The Ascent of Money: The Financial History of the World
As the world continues to struggle to find its footing amid rising unemployment, constricted credit and crumbling banks and industries — raising questions about how the economic system collapsed — PBS presents Niall Ferguson’s ASCENT OF MONEY. This groundbreaking four-part series examines the creation of the economic system by taking viewers on a global trek through the history of money. (An abbreviated version of the documentary, which focused on the current economic crisis at the advent of the Obama administration, aired in January; it can be streamed in full on the Website.) The four-hour version delves deeper into how the complex system of global finance evolved over the centuries, how money has shaped the course of human affairs and how the mechanics of this economic system work to create seemingly unlimited wealth — or catastrophic loss.
ASCENT OF MONEY is based on Ferguson’s best-selling book The Ascent of Money: A Financial History of the World, which predicted the current economic crisis and was released within weeks of the meltdown of sub-prime loans.
Said Ferguson, “In the midst of a major economic depression, it is often hard to appreciate the historical precedents and truly understand that while a situation may look dire, our system of finance, banking and trade has allowed for unprecedented progress. I’m hopeful the film will allow viewers to better understand the on-going evolution of our financial system and how our economy remains extraordinarily viable even as we are grappling with a crisis of historic proportions.”
For millions of people, the recession has generated a thirst for knowledge about how our global economic system really works, especially when so many financial experts seem to be equally baffled. In ASCENT OF MONEY, economist, author and historian Ferguson offers insight into these questions by taking viewers step-by-step through the milestones of the financial history that created this system, visiting the locations where key events took place and poring over actual ledgers and documents — such as the first publicly traded share of a company — that would change human history. Ferguson maintains that the history of money is indeed at the core of our human history, with economic strength determining political dominance, wars fought to create wealth and individual financial barons determining the fates of millions.
Among the places Ferguson visits are Bolivia, where Spain established vast gold and silver mines — still in operation — and enslaved the indigenous people to create so much currency for the Spanish crown that it eventually became worthless; Italy, where the Medici family transformed the sinful practice of usury into the banking system we know today and in the process became as powerful as monarchs; Paris, where Scotsman John Law created a Ponzi scheme tied to the Louisiana territory that brought France to its knees; London, where bonds trader Nathan Rothschild and his family nearly went bankrupt by helping to finance the British army’s war against Napoleon, then achieved enormous wealth through the buying and selling of war bonds; Scotland, where two ministers established the first life insurance fund, and New Orleans, where the shortcomings of their calculations would be demonstrated to tragic effect in the wake of Hurricane Katrina; and New York, where Ferguson interviews financial wizard George Soros about the concept he introduced of short selling derivatives based on a prediction that they will lose value.
Through this history, viewers learn economic fundamentals that inform the meanings of sub-prime mortgages and credit default swaps and an understanding how the Chinese economy has risen to dominate the world.
Subscribe to:
Posts (Atom)